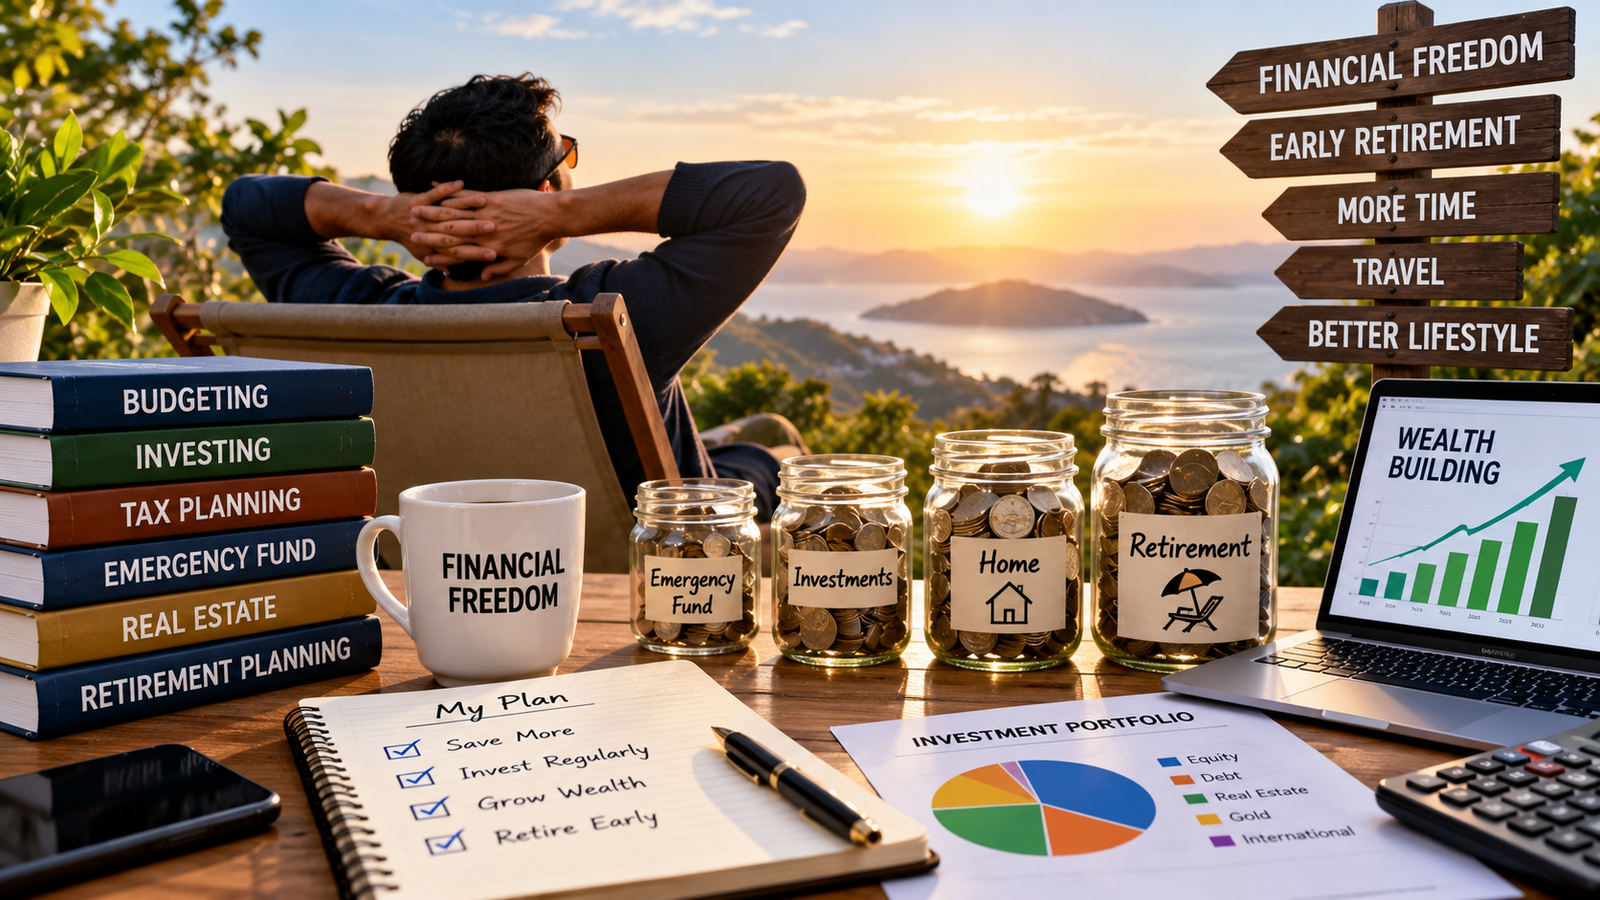
How a Salaried Person Can Retire Early: A Practical Wealth-Building Plan for Financial Freedom

Most salaried people assume retirement will happen somewhere around 60.
Work for decades.
Pay EMIs.
Raise children.
Save whatever remains.
Then hope EPF, pension, mutual funds and savings are enough.
But there is another way to think about retirement.
You do not necessarily retire when you reach a certain age.
You can retire when your investments can sustainably pay for your lifestyle.
That is the basic idea behind financial independence.
And for a salaried employee, the biggest advantage is not necessarily a huge salary.
It is time, consistency and compounding.
First, Understand Your Retirement Number
Before asking which mutual fund to buy, calculate how much money you actually need.
Suppose your current household expenses are:
₹60,000 per month
That is:
₹7.2 lakh per year
A commonly used financial-independence guideline is to build approximately 25 to 30 times annual expenses.
Using 25 times expenses:
₹7.2 lakh × 25 = ₹1.8 crore
Using a more conservative 30 times:
₹7.2 lakh × 30 = ₹2.16 crore
That becomes your approximate financial-independence target in today’s money.
But there is one major complication:
inflation.
If retirement is 15 or 20 years away, your future expenses will be much higher.
So your investment strategy has to grow faster than inflation.
Your Savings Rate Matters More Than Your Salary
Someone earning ₹2 lakh per month but spending ₹1.9 lakh may never become financially independent.
Someone earning ₹1 lakh and investing ₹40,000 every month may eventually build substantial wealth.
The key number is your savings rate.
If you save only 10% of your income, early retirement becomes difficult.
If you can gradually reach:
20% — good
30% — strong
40% — excellent
50%+ — potentially transformative
your timeline can shorten dramatically.
This does not mean living miserably.
It means deliberately avoiding expenses that permanently increase your monthly financial burden.
Lifestyle Inflation Is the Silent Retirement Killer
Most people do not remain poor because they never receive salary increases.
They remain financially dependent because every salary increase creates a lifestyle increase.
₹60,000 salary becomes ₹80,000.
Then comes a larger car EMI.
₹80,000 becomes ₹1.2 lakh.
Then comes a more expensive apartment.
₹1.2 lakh becomes ₹1.5 lakh.
Then restaurants, subscriptions, gadgets and vacations become more expensive.
Eventually the person earns three times more but still says:
“I have nothing left at the end of the month.”
The better strategy is simple:
Whenever your salary increases, invest at least half of the increment.
If your salary rises by ₹10,000, increase your SIP by ₹5,000 or more.
Your lifestyle still improves.
But your wealth accelerates too.
Start With One Powerful Habit: Step-Up SIP
Suppose you begin investing ₹20,000 per month.
If your investments average 12% annually over the long term, the corpus could grow roughly to:
₹46 lakh in 10 years,
₹1.8 crore in 20 years,
and around ₹3.5 crore in 25 years.
These are illustrations, not guaranteed returns.
But there is a more powerful strategy.
Increase your SIP by 10% every year.
Year 1: ₹20,000 per month
Year 2: ₹22,000
Year 3: ₹24,200
Year 4: ₹26,620
and so on.
For salaried professionals whose income increases over time, step-up investing can make a much bigger difference than constantly searching for the “best” mutual fund.
Your Portfolio Does Not Need 15 Mutual Funds
Many investors confuse complexity with sophistication.
They own:
three small-cap funds,
two mid-cap funds,
four flexi-cap funds,
sector funds,
gold funds,
international funds,
and stocks they bought after watching social media videos.
That often creates duplication rather than diversification.
A salaried investor can build a strong long-term portfolio with just a few broad categories.
For example:
50–60% — broad-market index or diversified large/flexi-cap equity
15–25% — mid-cap exposure
5–15% — small-cap exposure
10–20% — debt, EPF, PPF, bonds or other lower-volatility assets
The exact allocation depends on age, risk tolerance and retirement timeline.
The important principle is:
equity builds wealth; safer assets protect wealth.
As retirement approaches, gradually increase the safer portion.
Build an Emergency Fund Before Chasing Returns
Early retirement planning collapses if every emergency forces you to sell investments.
Before aggressively investing, build approximately 6–12 months of essential expenses in liquid, low-risk savings.
If your essential monthly expenses are ₹50,000, your emergency reserve could be roughly:
₹3 lakh to ₹6 lakh.
This money is not supposed to produce extraordinary returns.
Its job is to prevent you from selling equity during:
job loss,
medical emergencies,
family emergencies,
or market crashes.
Financial independence begins with financial resilience.
Avoid Bad Debt Aggressively
Not all debt is equally harmful.
A reasonable home loan for a house you can afford may be manageable.
But high-interest consumer debt can destroy compounding.
Credit-card balances.
Personal loans for vacations.
Expensive car loans.
Buy-now-pay-later spending.
If your investment earns 10–12% while your debt costs 18–30%, you are moving backward.
The fastest guaranteed “return” is often eliminating high-interest debt.
Do Not Buy a Bigger House Just Because the Bank Approves It
Housing is one of the biggest reasons salaried families delay retirement.
Suppose a bank tells you that you qualify for a ₹1 crore home loan.
That does not mean you should take it.
A giant EMI can lock your future salary into the present.
Instead ask:
Will this house improve my life enough to justify working an extra 5–10 years?
For some families, the answer may be yes.
For others, renting longer or buying a smaller property may dramatically accelerate financial independence.
Every recurring expense has a retirement cost.
Increase Income—Not Just Investment Returns
There is a limit to how much you can save from a small salary.
Eventually the fastest path to financial independence becomes increasing income.
A salaried professional should continuously ask:
Can I change companies?
Can I gain a certification?
Can I move into management?
Can I learn AI, analytics, finance or another higher-value skill?
Can I negotiate better?
Can I freelance?
Can I build a side business?
Saving ₹5,000 more is useful.
Increasing income by ₹30,000 while keeping lifestyle expenses stable can transform your financial future.
Your career is often your biggest wealth-building asset during your 20s, 30s and early 40s.
Build Multiple Sources of Wealth
Do not confuse early retirement with immediately replacing your salary using dividends.
During the accumulation phase, the priority should usually be growing the total portfolio.
Eventually your wealth may include:
equity mutual funds,
EPF or retirement accounts,
fixed-income investments,
property,
gold,
and perhaps business income.
Later, these assets can produce a combination of:
withdrawals,
interest,
dividends,
rent,
and capital appreciation.
Financial independence becomes safer when retirement income does not depend entirely on one asset.
The 4% Rule Is a Starting Point, Not a Guarantee
One popular retirement concept suggests withdrawing approximately 4% of a diversified portfolio in the first year of retirement, then adjusting withdrawals over time.
That is where the rough 25-times-expenses calculation comes from.
If you need ₹8 lakh per year:
₹8 lakh ÷ 4% = ₹2 crore
But early retirees should be more cautious.
Someone retiring at 40 may need money to last 50 years.
That creates:
market risk,
inflation risk,
healthcare risk,
and longevity risk.
For very early retirement, planning around a lower withdrawal rate or building 30–35 times annual expenses may provide greater safety.
Health Insurance Is Part of Retirement Planning
One serious medical event can destroy years of savings.
Do not assume that because your employer provides health insurance today, you will remain protected after leaving your job.
Build independent health coverage before retirement.
Similarly, people with financial dependents should consider adequate term life insurance.
Insurance is not primarily an investment.
It is protection against catastrophic financial events.
Do Not Retire With Zero Income
Early retirement does not have to mean sitting at home doing nothing.
A better objective may be work-optional life.
Suppose your investments can cover 80% of your expenses.
You could work part-time.
Consult.
Teach.
Freelance.
Run a small business.
Manage investments.
Or work only on projects you enjoy.
Earning even ₹20,000–₹30,000 monthly after leaving full-time employment can dramatically reduce how much retirement corpus you need to withdraw.
Financial independence is ultimately about choice, not unemployment.
A Simple Example
Imagine a 30-year-old salaried professional earning ₹1 lakh per month.
They decide to invest:
₹30,000 every month,
increase the SIP by 10% annually,
avoid expensive consumer debt,
maintain an emergency fund,
and invest salary increases instead of immediately increasing lifestyle expenses.
If their career progresses and they maintain that discipline for 15–20 years, they could potentially build a multi-crore portfolio.
The exact outcome depends on investment returns, income growth, inflation and taxes.
But the underlying mathematics is powerful.
The first crore feels difficult because most of it comes from your savings.
Later crores become easier because your existing money begins producing significant money of its own.
That is compounding.
The Real Secret of Early Retirement
There is no secret stock.
No guaranteed multibagger.
No magic mutual fund.
The formula is surprisingly boring:
Earn more.
Spend intentionally.
Avoid destructive debt.
Invest consistently.
Increase investments every year.
Let compounding work for decades.
Most importantly:
Do not repeatedly interrupt compounding.
People frequently invest for five years, withdraw everything for a car or expensive wedding, restart, withdraw for another purchase, and then wonder why wealth is not growing.
Long-term wealth needs uninterrupted time.
Conclusion: Buy Freedom Before You Buy Status
Every salary gives you two choices.
You can convert it entirely into lifestyle.
Or you can convert part of it into assets.
Lifestyle gives comfort today.
Assets can eventually buy your time.
The person who spends everything may look wealthy.
The person quietly accumulating assets may actually become wealthy.
That is the mindset salaried employees need to understand.
Early retirement does not require hating your job.
It means reaching a point where your next paycheck is no longer necessary for survival.
That is real financial freedom.
You may still work.
But you work because you choose to—
not because your EMI is due next week.
Frequently Asked Questions
How much money do I need to retire early?
A commonly used starting point is approximately 25–30 times your annual expenses, with more conservative planning appropriate for very early retirement.
Can I retire early with a normal salary?
Potentially yes. Your savings rate, income growth, investment discipline, expenses and time horizon matter more than salary alone.
How much should a salaried person invest every month?
Start with whatever is sustainable, but gradually targeting 20–40% of take-home income can materially accelerate wealth creation.
Are mutual funds enough for early retirement?
Diversified equity mutual funds can be an important part of long-term wealth creation, but retirement portfolios should also include emergency savings, insurance and lower-volatility assets.
Should I stop investing during a market crash?
Long-term investors often benefit from continuing disciplined investments during downturns rather than attempting to perfectly time markets, assuming their financial situation and risk tolerance remain unchanged.
Is ₹1 crore enough to retire?
It depends entirely on expenses. Someone spending ₹3 lakh annually and someone spending ₹15 lakh annually require very different retirement portfolios.
Disclaimer: This article is for educational purposes and does not constitute personalized financial advice. Investment returns are not guaranteed. Taxes, inflation, risk tolerance, insurance needs and individual circumstances should be considered before making investment decisions.
