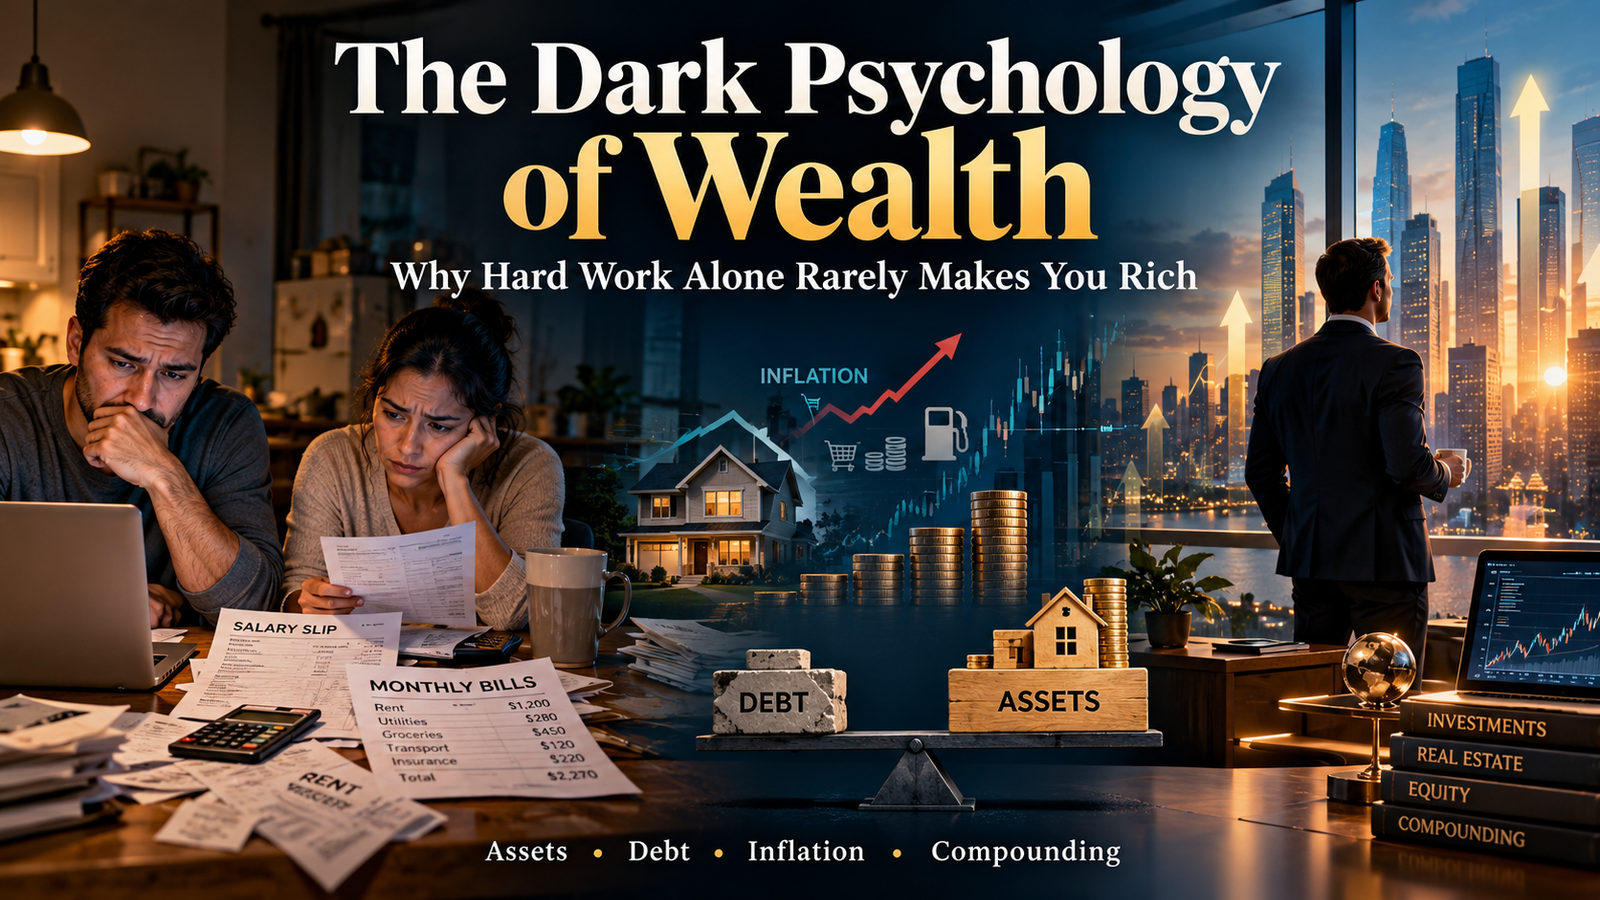

Most people grow up hearing a simple formula:
Study hard. Get a good job. Save money. Work harder.
Follow those rules and financial security should eventually arrive.
Yet millions of people do exactly that and still find themselves living from one salary to another.
Their income rises, but so do their mortgage payments, rent, insurance, taxes, groceries, cars and lifestyle expenses.
Meanwhile, someone who already owns businesses, stocks or real estate can see their wealth increase without working additional hours.
This is where the uncomfortable psychology of wealth begins.
The financial system does not literally “steal” every hardworking person’s money. But it often rewards ownership, capital and compounding differently from labour and consumption.
Understanding that distinction can change how you think about money.
The Middle Class Usually Sells Time
For most households, income follows a straightforward equation:
Time → Work → Salary
You work for eight hours and get paid.
Stop working long enough, and eventually the income stops too.
There is nothing wrong with employment. A salary can provide stability, benefits and the capital needed to build wealth.
The problem begins when salary becomes the only source of wealth creation.
A person’s time is limited.
No matter how hardworking you are, there are still only 24 hours in a day.
Capital does not have the same limitation.
Money invested in productive assets can continue working while its owner sleeps.
The Wealthy Own More Than They Consume
This is perhaps the biggest difference.
Middle-income households often hold much of their wealth in their home, cash savings and pensions.
At higher levels of wealth, portfolios increasingly contain business ownership, equities, investment funds and other financial assets.
OECD research finds that housing represents roughly 65% of household wealth for middle-wealth households across the countries it studied, while the wealthiest households hold a substantially greater portion of their wealth in financial assets.
That difference matters.
A car generally loses value.
A luxury phone usually loses value.
Most consumer goods lose value.
A productive business, stock portfolio or income-generating property has the potential to produce cash flow or appreciate.
One group primarily buys things.
Another increasingly buys things that can produce more money.
The Invisible Enemy: Inflation
Imagine keeping ₹10 lakh or $10,000 in cash for many years.
The number on the bank statement may remain unchanged, but what that money can purchase can decline as prices rise.
This creates an important psychological trap.
People often think:
“I haven’t lost money because my balance hasn’t fallen.”
But wealth is ultimately about purchasing power, not simply the number displayed in an account.
People who own assets may sometimes benefit when nominal asset values rise over long periods.
People who hold excessive idle cash can watch purchasing power erode.
That does not mean everyone should immediately invest everything. Emergency savings remain essential.
The lesson is simply that saving and investing perform different jobs.
Compound Growth Changes Everything
One of the biggest advantages wealthy households can develop is not intelligence.
It is time multiplied by capital.
Compound growth occurs when returns begin generating additional returns.
The U.S. Securities and Exchange Commission illustrates the concept simply: $100 earning 5% becomes $105 after one year, and the following year the return is earned on the larger amount rather than only the original $100.
Do that across decades and the difference becomes enormous.
The same mathematics can work against consumers through high-interest debt.
Compounding can therefore be either:
your employee or your employer.
You want your investments compounding for you—not credit-card balances compounding against you.
Why Lifestyle Inflation Keeps People Trapped
There is another psychological phenomenon that has little to do with government or financial markets.
It is status consumption.
Someone earns ₹50,000 per month.
They get promoted and earn ₹75,000.
Soon the inexpensive phone becomes a flagship phone.
The basic car becomes an expensive car.
Rent increases.
Restaurants become more frequent.
Subscriptions accumulate.
Income rose 50%.
Net worth barely changed.
This is lifestyle inflation.
Society teaches us to display success through consumption.
But visible wealth and actual wealth are very different things.
The person driving the most expensive car in your neighbourhood may be wealthy.
They may also have a very large monthly payment.
The Rich Often Think in Terms of Assets, Not Salaries
There is no single “millionaire mindset,” and wealth can come from entrepreneurship, inheritance, unusually high income, investment returns, luck, access to opportunities or combinations of these.
Still, a useful distinction exists.
An average employee may ask:
“How much does this job pay?”
An investor asks:
“What return can this capital generate?”
An entrepreneur asks:
“Can this system earn money without requiring every hour of my personal time?”
The shift is from:
earning → saving → spending
toward:
earning → acquiring assets → reinvesting → compounding
That does not happen overnight.
But repeated over 10, 20 or 30 years, the difference can become substantial.
The Wealth Gap Is Not Just About Mindset
This point is important.
Telling struggling families that they simply have the “wrong mindset” ignores reality.
Income, inheritance, housing costs, healthcare, education, geography, family responsibilities and access to capital all influence wealth accumulation.
OECD research finds that wealth is considerably more concentrated than income, with financial assets playing an important role in that inequality.
Homeownership has also become increasingly difficult for younger and lower-wealth households in many countries as property prices have risen.
So mindset matters.
But starting conditions matter too.
Financial literacy cannot magically turn a low income into millions.
What it can do is help someone make better decisions with the resources they have.
How Can a Middle-Class Person Break the Cycle?
The first goal should not be becoming a millionaire overnight.
It should be gradually shifting from being only a worker and consumer toward becoming an owner.
Start with five principles:
- Build a financial buffer. Keep emergency savings so unexpected expenses do not automatically become expensive debt.
- Eliminate destructive debt. High-interest consumer debt can compound faster than your investments.
- Invest consistently. Diversified investments allow ordinary households to own pieces of productive businesses. All investing carries risk, so diversification, costs and time horizon matter.
- Increase earning power. Skills, professional qualifications, entrepreneurship and career moves can increase the amount available to invest.
- Buy assets before upgrading lifestyle. When income increases, consider increasing investments before increasing consumption.
The goal is not to stop enjoying life.
It is to avoid spending every future income increase before it arrives.
The Most Important Mindset Shift
Perhaps the most useful financial question is not:
“How can I earn more money?”
It is:
“How much of the money I earn can eventually produce more money for me?”
Hard work still matters.
Education still matters.
Income still matters.
But labour alone has limits.
Ownership changes the equation.
Once you begin accumulating productive assets, even slowly, your financial life gradually stops depending entirely on your next salary.
That is the transition many wealthy people eventually achieve.
Not from employee to billionaire.
But from working exclusively for money to having some money working alongside them.
Conclusion
The uncomfortable truth about wealth is that modern economies generally reward both labour and capital—but they do not reward them in exactly the same way.
Workers earn income.
Owners participate in the growth and cash flows of assets.
The biggest opportunity for an ordinary middle-class household is therefore not discovering some hidden financial secret.
It is understanding the rules early enough to participate.
Earn.
Protect.
Invest.
Own.
Reinvest.
Then give compounding the one ingredient nobody can manufacture later:
time.
Frequently Asked Questions
Why do the rich keep getting richer?
One reason is that wealthier households typically own more appreciating and income-producing assets. When businesses, equities or real estate increase in value, existing owners benefit.
Is working hard useless for becoming wealthy?
No. Income is usually the starting point for building capital. The limitation is relying exclusively on salary without converting part of that income into assets.
What is the biggest difference between middle-class and wealthy finances?
A useful distinction is the proportion of income and net worth directed toward consumption versus productive assets. It is not universal, but asset ownership becomes increasingly important as wealth rises.
Can an ordinary salaried person become wealthy?
Yes, although outcomes vary considerably. Increasing income, controlling debt, investing consistently and allowing sufficient time for compounding can materially improve long-term financial security.
Should I invest instead of saving?
They serve different purposes. Emergency and short-term money generally needs safety and liquidity, while long-term capital may be invested according to an individual’s risk tolerance and financial goals.
Disclaimer: This article is for educational and informational purposes only and does not constitute financial, investment, tax or legal advice. Investment returns are not guaranteed, and all investments involve risk.
